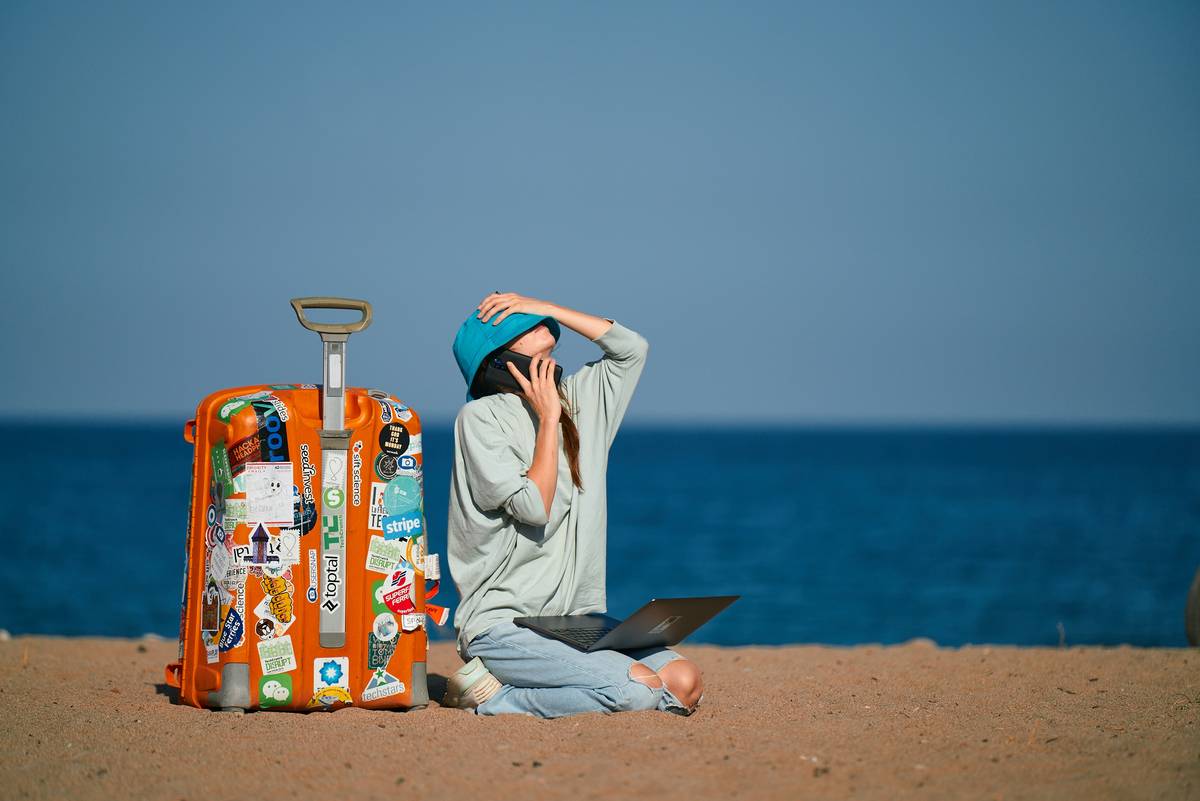
What if your dream side hustle overseas became a financial nightmare because you skipped one critical safeguard? I learned this the hard way when my camera gear—essential for my freelance travel photography gigs—was stolen in Lisbon. No insurance. No reimbursement. Just a $2,300 lesson in humility. If you’re juggling side gigs to make money while exploring the world, traditional travel insurance often leaves you exposed. This guide cuts through the noise with actionable steps, real examples, and expert-backed tips so your hustle stays protected—and profitable.
Table of Contents
- Why Travel Insurance Fails Gig Workers
- Step-by-Step Guide to Getting Covered
- Best Practices for Gig Worker Protection
- Real-World Case Studies
- Frequently Asked Questions
Key Takeaways
- Standard travel policies rarely cover income loss or equipment damage from freelance work abroad.
- Specialized gig worker insurance fills gaps left by mainstream providers—often for under $50/month.
- Always disclose your work activities to insurers; omitting them voids coverage.
- Pair your policy with emergency medical evacuation coverage if working in remote areas.
Why Travel Insurance Fails Gig Workers
Most travelers buy insurance thinking it’s a safety net for lost luggage or canceled flights. But if you’re earning money on the road—whether driving for rideshares, freelancing, or selling digital products—you’re operating in a gray zone. Standard policies treat “work” as incidental tourism, not income generation. The fine print often excludes “professional activities,” meaning a damaged laptop or missed client deadline due to illness won’t be covered.
I once assumed my global health insurance covered my writing gigs. During a bout of food poisoning in Bangkok, I missed a $1,200 deadline. My claim was denied because my policy didn’t include “income protection for remote work.” According to the U.S. Travel Insurance Association, over 60% of gig workers don’t realize their standard plan excludes occupational risks (USTIA Consumer Guidelines). That’s not just a gap—it’s a liability trap.
Step-by-Step Guide to Getting Covered
1. Audit Your Gig Activities
List every income stream: dog walking via Rover, Airbnb hosting, or selling prints on Etsy. Note equipment used (cameras, drones, laptops) and locations worked.
2. Compare Specialized Providers
Seek insurers like SafetyWing or World Nomads that offer “digital nomad” or “freelancer add-ons.” Verify they cover equipment theft, trip interruption due to work emergencies, and liability claims.
3. Disclose Everything Honestly
Never downplay your work as “just for fun.” Insurers need accurate risk profiles. Omission = automatic denial.
4. Bundle Medical Evacuation
If working off-grid (think Bali co-working hubs or Costa Rican surf towns), add emergency medical transport. It’s often excluded in basic plans.
Best Practices for Gig Worker Protection
- Avoid the “terrible tip”: Don’t rely on credit card travel insurance—it almost never covers gig-related losses. One major bank’s policy explicitly excludes “any activity generating income.”
- Renew policies monthly if your income fluctuates; annual plans may overcharge during slow seasons.
- Store digital proof of equipment value (receipts, serial numbers) in cloud storage accessible offline.
- Check local laws: Some countries (e.g., Portugal’s D7 visa) require proof of income stability—which insured gigs can support.
My biggest pet peeve? Insurers marketing “comprehensive” plans while burying gig exclusions in clause 8.3(a). Read the full policy wording—not just the brochure.
Real-World Case Studies
Sarah, a food blogger running Instagram tours in Mexico City, totaled her scooter during a client shoot. Her gig-specific policy from Heymondo covered $3,000 in medical bills plus $800 for lost tour income—something her old Allianz plan would’ve denied. Similarly, Dev, a coder doing contract work across Southeast Asia, used SafetyWing to recoup $1,500 after his MacBook died pre-deadline. These aren’t outliers; they reflect a growing market. Per a 2023 Upwork report, 59 million Americans freelanced last year—with 12% working remotely abroad (Upwork Freelance Forward Report).
Frequently Asked Questions
Does travel insurance cover Uber or Lyft drivers abroad?
No—standard policies exclude commercial vehicle use. You’ll need a local rideshare endorsement or specialized expat auto insurance.
Can I get gig insurance if I’m already traveling?
Yes. Providers like SafetyWing offer rolling monthly coverage purchasable mid-trip.
Are taxes affected by gig worker insurance claims?
Reimbursements for lost income are typically non-taxable as they replace earned revenue, not new income. Consult a CPA via our Contact Us page for personalized advice.
What’s the cheapest gig-friendly plan?
Budget options start at $40/month but skimp on equipment coverage. Aim for $60–$80/month for robust protection. Always cross-check with our About Us team’s latest comparisons.
Conclusion
Nailing side gigs to make money shouldn’t mean gambling your finances on shaky coverage. With the right insurance, you turn volatility into opportunity—earning confidently from anywhere. Ready to lock in your safety net? Reach out to us for a free policy review. And remember: adventure is best enjoyed with a backup plan. Don’t wander uninsured—your hustle depends on it.
Your passport’s stamped. Your skills are sharp. Now protect what powers your journey.